Cooperative Financing for Ghanaian SMEs: How Susu Groups, Credit Unions and Cooperatives Can Fund Your Business
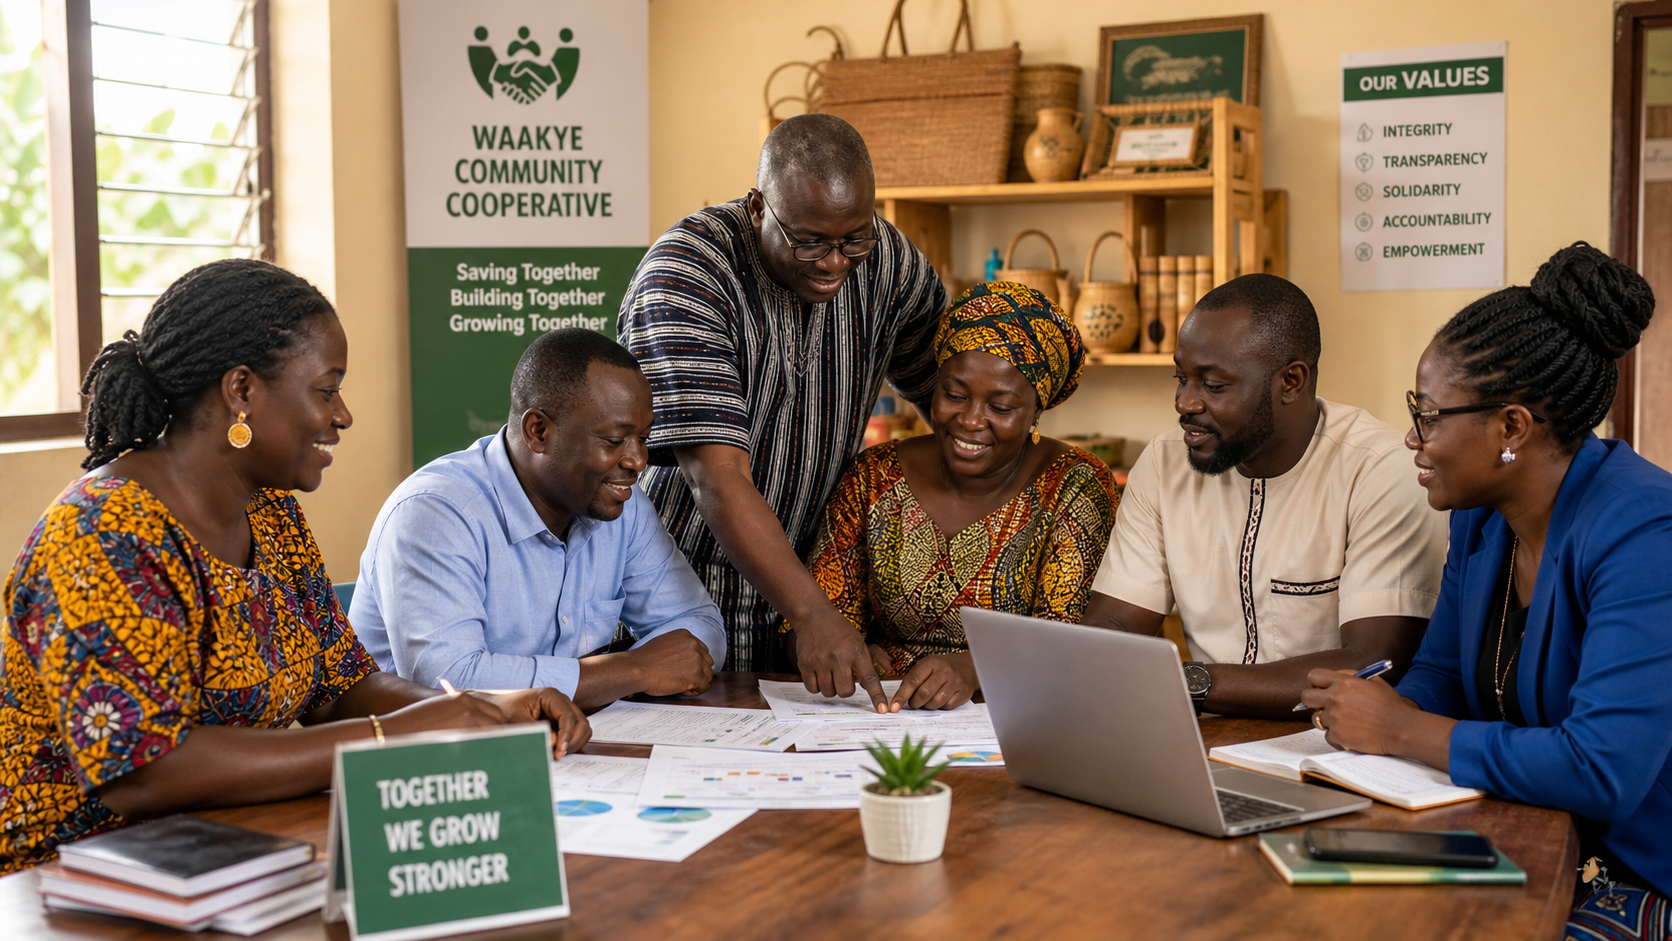
For many Ghanaian SME owners, the path to business credit does not begin at a commercial bank. It begins in a community — a susu group that pools weekly contributions, a credit union that lends to its members, or a cooperative society that organises collective economic activity. These member-based institutions have long served as a first port of call for entrepreneurs who lack the collateral or credit history that formal banks require.
But cooperative finance in Ghana is not a single, uniform system. A susu arrangement, a credit union and a registered cooperative society each operate under different legal frameworks, different supervisors and different rules about who can borrow and on what terms. Understanding these distinctions — especially in the context of the Bank of Ghana's revised 2026 microfinance framework — is essential before you commit your savings or sign a loan agreement.
The three cooperative finance models explained
Ghana's cooperative finance landscape is best understood through three distinct models. Susu groups and savings arrangements — including rotating savings and credit associations — allow members to save collectively or through a susu collector, with accumulated funds sometimes made available to participants in turn. Under the Bank of Ghana's January 2026 framework, susu collectors and savings associations fall within the Last-Mile Provider category. Some groups remain informal rather than regulated deposit-taking institutions, so the level of oversight and member protection can vary considerably.
Credit unions are member-based organisations that provide both savings and credit services. Access to loans is tied to membership and the union's own registered by-laws. Under the 2026 framework, a credit union whose total assets are consistently at or above GH¢60 million for one year is licensed and supervised directly by the Bank of Ghana. Smaller credit unions are classified as Last-Mile Providers under delegated supervision — an important distinction that affects the level of regulatory oversight and the protections available to members.
Cooperative societies are registered legal bodies formed to advance members' shared economic interests under the Co-operative Societies Act, 1968. They are registered and overseen by the Department of Co-operatives. A cooperative society is not automatically a deposit-taking institution or a lender — its actual financial activities depend on its registered by-laws. In agriculture, for example, the Feed Ghana Programme encourages Farmer Based Organizations to transition into formally registered cooperatives to better access inputs, financial support and market linkages.
Who regulates what: the key institutions
Several institutions shape Ghana's cooperative finance environment. The Bank of Ghana regulates the financial sector categories established by its revised framework. It directly licenses and supervises credit unions meeting the GH¢60 million asset threshold, while smaller credit unions and other Last-Mile Providers fall under delegated supervision. The Department of Co-operatives handles the registration and governance oversight of cooperative societies under the Co-operative Societies Act.
The Ghana Co-operative Credit Unions Association (CUA) is a sector association within the credit union space. It does not function as a direct retail lender to every SME — the lending relationship is with the individual credit union, not CUA itself. ARB Apex Bank, historically a central support institution for Rural and Community Banks, has had its mandate expanded under the 2026 framework to provide centralised services — including liquidity support, cheque clearing and shared digital infrastructure — across all four institutional categories. This expanded role does not mean SMEs can apply to ARB Apex Bank directly for business loans.
The Bank of Ghana's 2026 framework: what changed
The most significant recent development for Ghana's cooperative finance sector is the Bank of Ghana's revised microfinance framework, issued on 27 January 2026 as Notice No. BG/GOV/SEC/2026/03. It replaces the 2011 operating rules and reorganises the sector into four categories: Microfinance Banks, Community Banks, Credit Unions and Last-Mile Providers. The framework is designed to reduce regulatory fragmentation, strengthen governance and resilience, and integrate the sector through shared technology.
For existing institutions, the transition timeline is active. Rural Banks were required to convert to the Community Bank model by 31 March 2026 and complete name changes and regulatory alignment by 31 December 2026. Eligible institutions had to notify the Bank of Ghana of their transition route by 30 June 2026, with progress reports due by 30 September 2026. For SME owners, the practical implication is straightforward: a legacy business name or old description may no longer reflect an institution's current regulatory category. Always confirm the provider's current status before depositing money or accepting a loan.
How to access credit through a cooperative or credit union
Accessing cooperative credit typically starts with legal membership. Under the Co-operative Societies Act, a registered society generally restricts lending to its members, with limited exceptions for inter-society lending. This means the process begins before you need a loan — you must join, contribute and build a savings history according to the institution's rules. Eligibility and terms differ by institution; there is no single national loan formula verified across all cooperatives or credit unions.
A practical step-by-step approach would be to: verify that the society or credit union is registered and confirm its regulatory category; obtain and read its registered by-laws; apply for membership and satisfy the applicable contribution or savings requirements; build any savings history required by that institution; then request the loan policy and application form. Before signing anything, review the approved amount, total pricing, fees, security requirements, repayment schedule and default provisions in writing.
- Verify registration and regulatory category (Bank of Ghana-supervised or Last-Mile Provider)
- Read the registered by-laws and membership conditions before joining
- Confirm entrance fees, savings-history requirements and loan eligibility rules
- Request all loan terms — pricing, fees, security, repayment dates — in writing
- Keep copies of all membership, savings and loan records
Advantages and limitations for SME owners
Cooperative finance offers genuine advantages for SME owners who are prepared to engage with the membership model. A registered cooperative creates a formal legal body for collective economic activity. Credit unions provide a member-based channel for savings and credit that can be more accessible than commercial banks for businesses without extensive collateral or formal credit history. Cooperative registration can also position eligible agricultural groups to seek participation in government interventions such as the Feed Ghana Programme.
However, the limitations are equally important to understand. Membership does not guarantee credit. A cooperative society is not automatically a licensed deposit-taking institution. Smaller credit unions, susu collectors and savings associations fall within the Last-Mile Provider segment, not the same regulatory category as Microfinance Banks. Loan pricing and eligibility are not uniform across cooperatives or credit unions. The sector is also in active transition during 2026, meaning names, categories, supervisors and operating permissions may change. Government registration or programme alignment does not guarantee a grant, input allocation or loan.
What Ghanaian SME owners should do now
The safest approach in 2026 is to verify first and commit second. Before depositing money or accepting a loan from any cooperative, credit union or susu arrangement, confirm the institution's registration, its current regulatory category under the Bank of Ghana's 2026 framework, and its transition status if it was previously operating under the old rules. Ask who holds your money, what records will be issued, who supervises the provider, and what happens if the institution or a member fails to meet an obligation.
If you are considering forming a cooperative society, the process requires at least ten qualifying members, agreement on a shared economic purpose, preparation of by-laws, and submission of an application to the Registrar through the Department of Co-operatives. If the society intends to provide financial services, confirm whether additional Bank of Ghana requirements or the Last-Mile Provider framework apply before promoting any loan product. Whether you are joining an existing institution or forming a new one, written terms and verified registration are your most important protections.
Key takeaways
- Ghana's cooperative finance sector covers three distinct models — susu groups, credit unions and cooperative societies — each with different legal status, supervisors and lending rules.
- The Bank of Ghana's January 2026 framework reorganised the sector into four categories: Microfinance Banks, Community Banks, Credit Unions and Last-Mile Providers — always confirm which category your institution falls under.
- Credit unions with total assets at or above GH¢60 million are directly supervised by the Bank of Ghana; smaller ones operate as Last-Mile Providers under delegated supervision.
- Membership, savings history and compliance with a cooperative's registered by-laws are the typical gateway to borrowing — there is no single national loan formula.
- Verify registration, regulatory category and written loan terms before committing savings or signing any security document.
This article is provided for general information only and does not constitute financial advice. Programmes, rates and regulations referenced may change. Please verify details directly with the relevant institutions or authorities before making decisions.